For years, cash was often treated as money waiting to be invested. The assumption was simple: if your money wasn’t in stocks, real estate, or a business, it wasn’t doing enough to help you build wealth.
But cash has an important role in a strong financial plan—and that role goes beyond earning interest.
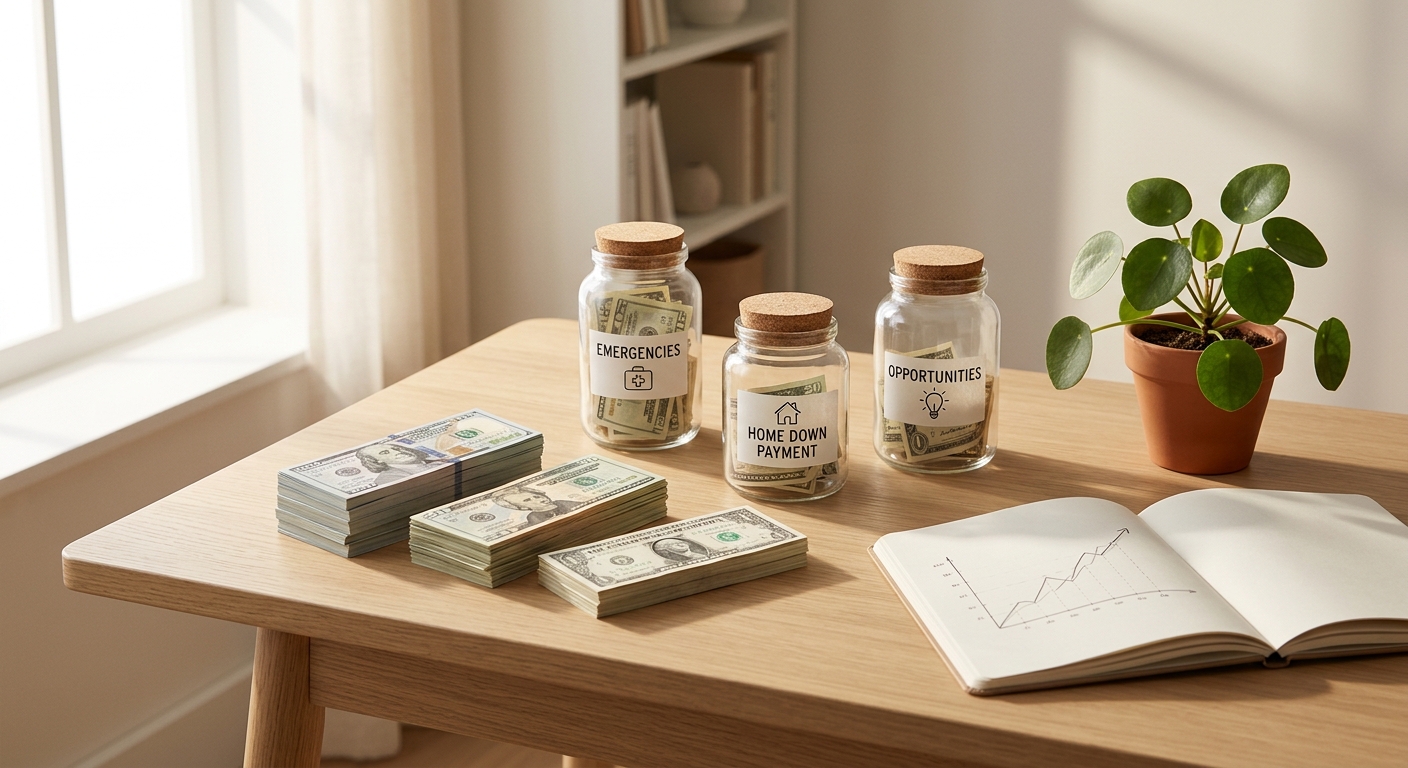
Cash can help you handle emergencies, cover upcoming expenses, avoid selling investments at the wrong time, and prepare for opportunities without taking unnecessary risks. When held in the right amount and in the right place, it can provide something every wealth-building plan needs: flexibility.
The key is knowing how much cash to keep, where to hold it, and what each dollar is supposed to do.
You don’t need a large portfolio to apply this principle. You can start with your paycheck, your savings account, and a clear plan.
What Does It Mean to Treat Cash as an Asset Class?
An asset class is a broad category of financial assets that share certain characteristics and often serve similar purposes in a portfolio.
Common asset classes include stocks, bonds, real estate, and cash or cash equivalents. Each can play a different role in a financial plan.
- Stocks can provide long-term growth, but their values fluctuate.
- Bonds can provide income and diversification, although they carry risks such as interest-rate and credit risk.
- Real estate may provide rental income or appreciation, but it can be expensive to maintain and difficult to sell quickly.
- Cash and cash equivalents can provide liquidity, stability, and access to money when you need it.
Treating cash as an asset class means deciding intentionally how much of your financial resources should remain readily available rather than being invested for potentially higher long-term returns.
It doesn’t mean keeping all your savings in a checking account or avoiding investing altogether.
It means recognizing that money has different jobs at different stages of your financial life.
Money for next month’s bills has a different purpose from money you’re investing for retirement 25 years from now. Your financial strategy should reflect that difference.
Why Cash Can Be Valuable in a Wealth-Building Plan
Cash may not have the excitement of a rising stock market or the long-term growth potential of a diversified investment portfolio. But its value becomes clear when you look at the problems it can help prevent.
1. Cash Gives You Financial Breathing Room
Life doesn’t always follow your budget.
Your car may need an unexpected repair. Your hours at work may be reduced. A medical expense may arrive at the wrong time.
Without accessible savings, you may have to rely on a credit card, take on expensive debt, or sell investments to cover the bill.
A cash reserve can help you absorb these surprises without derailing your broader financial plan.
That’s why an emergency fund is more than a savings goal. It is a layer of protection between an unexpected expense and the progress you’ve already made.
If you’re building your financial foundation, start with our guide to building wealth from scratch.
2. Cash Can Help You Avoid Selling Investments Under Pressure
Imagine you have money invested for long-term goals when the stock market experiences a significant decline.
At the same time, you face an unexpected expense.
If you don’t have accessible savings, you may need to sell investments while their values are down. That can turn a temporary market decline into a realized loss and leave less money invested for a potential recovery.
A suitable cash reserve can reduce the likelihood of being forced into that decision.
Cash doesn’t eliminate investment risk, and it cannot guarantee better results. But it can give you more choices when circumstances become difficult.
One of cash’s most important jobs is helping you leave your long-term investments alone when you need money for something else.
3. Cash Can Help You Prepare for Opportunities
Cash can also make it easier to act when a worthwhile opportunity appears.
You might need funds for a professional certification, a business investment, a home purchase, or another planned expense. Having money set aside for that purpose can help you act without relying entirely on borrowing.
Investors sometimes call money held for future investment opportunities “dry powder.” It refers to funds that are available to deploy when an appropriate opportunity arises.
However, keeping cash ready for a possible market decline is not a guarantee of better investment performance. Markets can rise while you’re waiting, and it can be difficult to know when prices have reached their lowest point.
For most households, the priority should be maintaining a sound emergency reserve and funding known near-term goals before setting aside additional cash for speculative opportunities.
Where Should You Keep Your Cash?
Not all cash accounts work the same way. The best place for your money depends on when you need it, how easily you must be able to access it, and what protections apply.
Here are some common options.
Checking Accounts
Checking accounts are designed for everyday transactions, including paying bills, buying groceries, and receiving your income.
They offer convenient access to money, but many pay little or no interest.
Keep enough here to cover routine expenses and manage your monthly cash flow. You may not need to keep all your savings in the same account.
High-Yield Savings Accounts
High-yield savings accounts can offer more interest than traditional savings accounts while keeping your money accessible.
They can be useful for emergency funds and goals that require relatively easy access to cash.
Before opening an account, review its current annual percentage yield (APY), fees, minimum balance requirements, withdrawal terms, and whether the institution is FDIC-insured.
Interest rates can change, so don’t assume that a competitive rate today will remain the same indefinitely.
Money Market Deposit Accounts and Money Market Funds
These names sound similar, but they refer to different financial products.
A money market deposit account is a bank deposit account that may pay interest and may qualify for FDIC insurance when held at an insured bank within applicable limits.
A money market fund is an investment product that typically holds short-term, high-quality debt securities. It may be available through a brokerage account and is not FDIC-insured. Although these funds are generally designed to maintain liquidity and a relatively stable value, they are investments and are not risk-free.
Read the product details carefully before deciding where to keep your money.
Certificates of Deposit (CDs)
A certificate of deposit generally pays a specified interest rate for a set term.
CDs may suit money you won’t need immediately, particularly when you want a predictable rate for a defined period.
The trade-off is access. Early withdrawals may trigger penalties, depending on the account terms.
If you use CDs for savings goals, consider staggering maturity dates so that some money becomes available at different times rather than locking up your entire reserve.
U.S. Treasury Bills
Treasury bills are short-term debt securities issued by the U.S. Treasury.
They can be useful for certain short-term savings strategies, particularly when you know approximately when you will need the money.
However, access and timing matter. Selling a Treasury bill before maturity may involve a market price that differs from what you paid, and you should align maturities with your spending needs.
Treasury bills are not the same as a bank savings account, so understand how they work before using them for money you may need immediately.
How to Choose the Right Place for Your Money
Don’t choose an account based on interest rate alone.
Ask yourself three questions:
- When will I need this money? Money needed for everyday bills should be easier to access than money earmarked for a goal several months away.
- How much risk can I accept? Emergency savings generally call for safety and accessibility, not the pursuit of higher returns.
- What will I pay or give up? Fees, withdrawal restrictions, penalties, and changing rates can affect the usefulness of an account.
For U.S. bank deposits, FDIC insurance generally protects eligible deposits up to $250,000 per depositor, per insured bank, per ownership category, subject to applicable rules. Credit union deposits may have comparable protection through the NCUA. Brokerage investments, including money market funds, are not bank deposits insured by the FDIC.
You can verify bank deposit coverage through the FDIC and learn more about Treasury securities at TreasuryDirect.
How Much Cash Should You Keep?
There isn’t one correct cash balance for everyone.
Your ideal amount depends on your essential expenses, income stability, dependents, debt obligations, upcoming purchases, and comfort with uncertainty.
A practical approach is to divide your cash into three broad purposes.
1. Everyday Cash
This is the money you use to run your life: rent or mortgage payments, utilities, groceries, transportation, and other regular expenses.
The amount you keep readily available depends on your pay schedule, bill due dates, and how you manage your monthly budget.
2. Emergency Savings
A common starting guideline is to build an emergency fund covering three to six months of essential expenses.
If your income varies significantly, you support dependents, or your job is less predictable, you may prefer a larger reserve. If you have a stable income and fewer financial obligations, a different target may make sense.
For example, if your essential expenses total $3,000 per month:
- Three months of expenses equals $9,000.
- Six months of expenses equals $18,000.
These are planning examples, not mandatory targets. Start with a manageable milestone and build consistently.
3. Cash for Planned Goals
This money is set aside for expenses you expect to face in the near future, such as a home down payment, vehicle purchase, education costs, or a major home repair.
Because these goals have a shorter timeline, protecting the money from substantial market fluctuations may be more important than pursuing investment growth.
Keep this category separate in your budget, even if you use more than one savings account or financial product to hold the funds.
Separating these purposes makes it easier to see which money is available to spend and which money is already committed.
The Risk of Holding Too Much Cash
Cash has benefits, but holding more than you need can create problems of its own.
Inflation Can Reduce Purchasing Power
When prices rise, the same amount of money buys less than it did before.
If your savings earn 2% interest while the prices of the goods and services you buy rise by 3%, your money’s purchasing power declines over that period, before considering taxes.
The relevant comparison is the return on your cash after taxes versus inflation. A positive account balance doesn’t necessarily mean your savings are keeping pace with the cost of living.
Cash May Miss Long-Term Growth Opportunities
Money kept in cash generally has less potential for long-term growth than a diversified portfolio of growth-oriented investments, although the portfolio also carries greater risk.
If money intended for retirement stays entirely in cash for decades, you may miss opportunities for investment growth and compounding.
That doesn’t mean you should invest your emergency fund in the stock market. It means you should distinguish between money you need to protect in the short term and money you can invest for the long term.
Interest Rates Can Fall
An attractive savings rate today may not last.
When interest rates decline, variable rates on savings accounts and money market deposit accounts may fall as well. Maturing CDs and Treasury bills may also need to be reinvested at lower rates.
Rather than building your entire strategy around today’s highest available rate, choose accounts that fit your needs and review them periodically.
Cash is valuable because of the job it does—not because it always delivers the highest return.
How to Put Cash to Work Without Overcomplicating Your Finances
You don’t need a complicated portfolio or a large amount of money to start using cash strategically.
Use these steps to create a simple system.
Step 1: Give Every Dollar a Job
Start by identifying what your money needs to accomplish.
Some dollars are for this month’s expenses. Some are for emergencies. Others are for goals within the next few years. Money intended for long-term goals may be suitable for investing, depending on your circumstances and risk tolerance.
This is the foundation of intentional money management: decide what each dollar is for before deciding where to keep it.
Our guide to building money systems instead of simply setting money goals explores how consistent habits can help you make progress over time.
Step 2: Build Your Financial Safety Net
If you don’t have emergency savings yet, start with a small, achievable target.
Your first goal might be $500 or $1,000, depending on your situation. From there, work toward a reserve that reflects your essential expenses and personal circumstances.
Automating a manageable transfer on payday can help you build the habit without having to make the decision from scratch each month.
Step 3: Match Your Savings to Your Timeline
Think about when you’ll need the money.
- Within the next few weeks: Prioritize easy access and stability.
- Within the next year or few years: Consider suitable savings accounts, CDs, or other short-term options that match your timeline and access needs.
- Many years away: Consider whether diversified investments are appropriate for the goal, based on your risk tolerance and overall plan.
These are broad guidelines rather than rigid rules. The important point is to avoid exposing money needed soon to risks you cannot afford to take.
Step 4: Review Your Cash Accounts
Check the interest rates, fees, restrictions, and protections on the accounts you already use.
If a substantial amount of savings is sitting in an account that pays very little, you may find a more suitable alternative. But don’t move money solely for a small rate difference without considering access, reliability, account requirements, and the time involved.
A simple system you understand and maintain is often more useful than a complicated arrangement you rarely review.
Step 5: Create a Regular Financial Check-In
Review your cash position every few months or whenever your circumstances change.
Ask yourself:
- Do I have enough money available for upcoming bills?
- Is my emergency fund appropriate for my current expenses?
- Am I saving for planned purchases separately from emergencies?
- Is any cash sitting idle without a clear purpose?
- Am I keeping too much in cash because I’m nervous about investing?
- Am I investing money that I may need too soon?
These questions help you adjust your plan as your life evolves.
Cash Is One Part of a Bigger Wealth Strategy
Building wealth isn’t simply about finding the investment with the highest return. It’s about balancing growth, protection, access, and consistency.
Cash can support that balance by helping you handle emergencies, prepare for near-term expenses, and avoid unnecessary financial pressure. Investments can play a different role by helping you pursue long-term growth.
Neither needs to replace the other.
The right balance depends on your goals, timeline, income, obligations, and willingness to accept risk.
If you want to connect these decisions to a broader financial direction, start by identifying your Wealth Target. Knowing what you’re working toward can help you decide how much money to protect, how much to invest, and how to prioritize the next step.
You don’t need to copy the strategies of wealthy investors to make thoughtful decisions with your money. You need a system that works for your life.
Cash isn’t the whole wealth-building plan. It’s the foundation that can help the rest of the plan work more effectively.
Leave a Reply